Table of Contents
Episode Summary
Listen On: Apple Podcast | Spotify
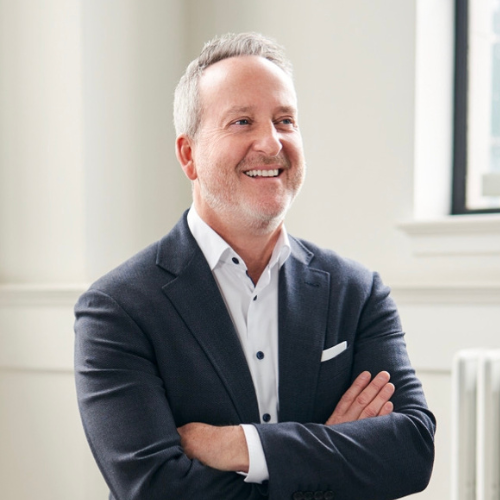
Daryl Simpson
Daryl has worked in the development industry since 1993, building a reputation as a highly respected market visionary. A high-rise and luxury-product expert, he has directed more than fifty towers and communities from concept to completion while playing a pivotal role in the creation of one of Canada’s finest development companies. Daryl possesses a passion for design, an innate ability to innovate, and hard-wired developer mindset.
Daryl is active in charitable and philanthropic endeavours, currently acting as Director for both Equitable Real Estate Investment Ltd and the Lotte and John Hecht Memorial Foundation. He is a past Director of Canuck Place Children’s Hospice Board, Executive Board Member of the Urban Development Institute, and Past-Chair of the UDI Education Committee.
Vancouver’s 2026 Housing Glut Is Quietly Building the Next Supply Crunch
Everyone’s looking at the cranes. Visitors keep pointing at them all summer, and it makes the talk of a frozen market sound like nonsense. But those cranes are finishing something. They’re not starting anything.
Daryl Simpson has been in this business since 1993, and the President of Townline calls the current condo market the slowest of his entire career. That part isn’t news to anyone selling right now.
Here’s the part that is. The same conditions killing demand today are switching off the pipeline for 2027 and 2028. And nothing started in those years means nothing delivered three and four years later.
So Metro Vancouver’s oversupply burns off. Then what? Simpson’s answer: a tougher, less balanced housing market in the early 2030s. Today’s glut is tomorrow’s shortage.
What You’ll Learn
- Why 20,000 rental units under construction don’t mean 20,000 more behind them
- The rent-forecasting change that kills projects before they’re ever drawn
- How far Metro Vancouver construction costs have come off — and how fast they snap back
- The subtrade shortage nobody’s pricing into 2029 budgets
- Why the next condo cycle demands more developer equity and smaller pre-sale stacks
- What a normal Vancouver market looked like before 2022, and why it wasn’t a bad thing
The Supply Everyone’s Pointing At Is Already Committed
Metro Vancouver has close to 20,000 units of multifamily rental under construction, roughly 14,000 of them concrete and the balance wood frame. About 5,000 units land next year. Another six or seven thousand land the year after. Some of it doesn’t deliver until 2029.
The key word is committed. Every one of those units was a decision made years ago, under different rents, different rates, different population math. They’re finishing. Nobody’s replacing them.
Why Nothing New Starts In 2027
Rent underwriting broke. That’s the whole story, and it’s less boring than it sounds.
Developers used to pencil a project by assuming rent grew about 5% a year. Start at five bucks a foot, forecast 5% three years running, and rents hit $5.75 by delivery. On paper, the debt gets serviced.
Then rents fell. Simpson can’t recall a time in Metro Vancouver when rents decreased before, and they’ve come down over the last year or two. The floor everyone depended on stopped being a floor.
So Townline is flatlining rent appreciation for this year and next, with moderate growth after that. Run a project with no rent lift for two years and it doesn’t pencil. Nobody builds what doesn’t pencil.
And the policy noise isn’t helping anyone decide. Simpson doesn’t know what the condo bailout program actually is, and says the industry never asked for it and was never consulted on it. What he does know is the effect: buyers and renters looking for a signal get confusion instead. One more reason to sit still.
“Effectively, nothing’s going to start next year. Nothing’s going to start in 2028.” — Daryl Simpson, President, Townline
Two vanished start years. Compounding into the early 2030s.
The Construction Discount Has An Expiry Date
Costs have come down. A middle-market concrete tower that was being pro formed at $475 a square foot at the peak now pro formas at $400 to $425.
But look at where that savings comes from. Excavation and shoring. Site works. Form work, to a degree. Glazing systems. Early trades — the ones pricing work they’ll perform soon.
Mechanical and electrical haven’t moved much at all. That equipment needs factory production, mostly outside Canada, which drags in tariffs and shipping. Those suppliers are holding their numbers. A supplier delivering an HVAC unit in three years has no idea what it’ll cost them, so they’re passing nothing on.
Simpson’s read is that the discount is temporary, not a reset. When the market gives developers and lenders a reason to move, pricing goes bang, right back up to the high fours.
Which is why Townline sees value in starting projects soon. It’s a window, and windows close.
The Subtrade Math Nobody’s Budgeting For
Here’s the piece that gets missed. A work shortage over the next year or two hits subtrades at the exact moment their principals are aging out, looking at the next turn of the cycle and deciding they don’t want to be there for it.
Retirements. Consolidation. A smaller pool to tender against.
“It’s actually going to create more competition for their work, and construction prices in the medium term, two to three, four years out, are not going to be lower, they’re going to be higher, because there are fewer subtrades to choose from when we’re tendering a job.” — Daryl Simpson, President, Townline
Fewer bidders means higher bids. That’s the cost curve nobody’s modelling into a 2029 delivery.
The Demand Side Doesn’t Wait For The Pipeline
Population has flatlined, and Simpson names that as part of why demand is so thin right now. He doesn’t think it holds.
His read: the federal government works out that this country needs a responsible amount of immigration to sustain and buttress the economy, and starts welcoming it back. He won’t call it a green shoot, because it hasn’t shown itself yet. He also can’t believe it isn’t coming.
Now line that up against the construction calendar. Immigration returns. Starts never happened in 2027 or 2028. The units that would have absorbed those people were never drawn.
Simpson thinks British Columbia is as well positioned as it’s ever been on the global stage, with the Middle East and the situation south of the border unlikely to resolve soon. More butts in seats, as he puts it. Whether there’s anything for them to move into is the open question.
What The Next Cycle Actually Looks Like
Simpson doesn’t think the market comes back in its old shape. The sales centre that sells out in a week, the project pre-sold from a boardroom, suites bought sight unseen — that was 2022, and he thinks it’s a long way off.
Instead: developers sell 25% or 30% of a project and put in more equity so the bank lends on the rest. Smaller pre-sale stacks. Banks being more accommodating about it.
And none of that restarts until rental stabilizes. Simpson sees the two markets as indicators of each other’s health, and pre-sales have always leaned on investor buyers who need a rental market they can believe in.
“It’s real homes for real people over a reasonable amount of time.” — Daryl Simpson, President, Townline
He points back at the early 2000s and the nineties, when the market moved two to five per cent a year and stayed predictable. That was affordable. That was fine, actually.
This correction is writing the terms of the next one. Are you positioned for the glut, or for what comes after it?
Episode Host
Adam Scalena
Adam is a full-service realtor, specializing in Vancouver’s best areas. His systematic approach to real estate and dedication to his clients has consistently placed him within the top 10% of realtors operating within Greater Vancouver.
Matt Scalena
Matt is real estate obsessed and considers himself a lifelong student of the Vancouver real estate market. As a co-manager of the Scalena Real Estate team, Matt prides himself on expertly advising buyers and sellers on all aspects of the fast-paced, dynamic Vancouver real estate market. He is present at every stage of the process, from that first phone call or email right through to when keys are exchanged between sellers and buyers.
Sponsors

Full Podcast Transcript – Interview with Daryl Simpson
This transcript has been lightly edited for clarity and readability.
Adam Scalena: We’re here with Daryl Simpson, President of Townline, but I like to think of him as a fan favourite and past guest of the show. Daryl, thanks so much for taking the time today.
Daryl Simpson: Thank you for having me on. Good to see you guys again.
Matt Scalena: Daryl, for people who are not familiar with you, and I feel like most people will be, can you start by telling our listeners a little bit about yourself?
Daryl Simpson: For sure. I started in the business in 1993. God, that seems like such a long time ago. I worked in real estate marketing and consulting for the first few years, and then went to work with developers, starting with Intrawest/Intracorp in 1995. I was there for a handful of years and then left to work with the Bosa family here in Vancouver for close to a quarter of a century. And I’m now the President of Townline.
So I’ve been around a long time. I probably said this to you in previous sessions, but I used to be the young guy in the room, and that switched. That’s funny, right? I used to be the young guy in the room and now I’m definitely not, and that hasn’t been the case for a long time.
Adam Scalena: I’m laughing partly because Matt and I had this conversation recently. We used to be the young agents in the room and that’s changed as well. Time’s flying.
Daryl, maybe just as a launching point, and it’s always different from different perspectives, of course we’re in the resale world and the market feels a bit different than the pre-sale world, but what’s your take on the market right now?
Daryl Simpson: By market, I think you’re asking about the condo for-sale market: condos, townhomes, that sort of thing. So maybe before I answer that question, I’ll explain for you guys and for the listeners where we operate along the housing spectrum as Townline.
We are very present and active in the non-market space through our TL Housing Solutions entity. We’re one of the largest providers of non-market housing to BC Housing and other government-funded procurement models. We are a private developer. We develop for ourselves and also with institutional partners like QuadReal, Nicola Wealth, Canderel, et cetera, and we develop market rental and market condo and townhome projects within what most people would know as Townline. And we also have a third-party construction business, which is Townline Construction. Rick Ilich started in construction in 1980, so we started as a construction company, and we’re now spending more and more time there building for other developers and other lenders and stakeholders in this market too. We may have time to talk about that later. Hopefully we do.
So we’re active in many areas of the housing spectrum. Back to your question: the condo market right now is the slowest it’s felt in my entire career. And that’s not a sensational statement. Lots of people I suspect that have been talking with you in the last three to six months would say similar things, but it’s incredibly slow.
Why is that? I think for owner-occupiers and first-time buyers, there’s generally a belief that there may be a better deal around the corner and that they may get paid to wait a bit. That may or may not be true in some markets, depending on how much inventory there is and how much distress there is in the individual market they’re looking at.
And from an investor standpoint, condo investors that have been such a driver of our market in the last, well, in my entire career, let’s say the last 20 years, those condo investors have a very low degree of consumer confidence right now. Why is that? Because they don’t believe that this region in the short term is going to generate the upside and lift in value that they would want to see. And therefore the return on their investment is hard to understand and hard to project over the next couple of years. The political environment that we operate in is a whole other discussion, which I’d also love to get into at some point if we have time.
So consumer demand and investor demand right now is very little. We have flatlined population, and that certainly factors into it. And we have seen a relative explosion in supply in the last couple of years, and we have more coming next year. So there are reasons for consumers and investors to be cautious. Although I think that’s going to change sometime. I don’t know how quickly, but we’re going to hit the bottom here, I think, pretty soon.
Matt Scalena: Daryl, you said 1993 was when you started, right? I’m thinking especially of Richard Whitstock, who I think is a friend of yours. He comes to mind as a guy who said that now feels like anywhere between the mid to late nineties. Of course, that was kind of the last time the NDP was in power for this long. Does this feel like the nineties to you? It sounds like it’s slower than when you started, at least in the condo market. Is there any analogous moment in your career?
Daryl Simpson: Sure. I think one of the profound differences between now and the late nineties was that this NDP government is worse than the last one. And so I think there’s more economic malaise and concern and contempt right now than there was back then.
I think that factors into a lot of things. It factors into developers’ mindset and risk profile and our desire to move projects forward, and it factors into a consumer’s mindset as well. There may be fears over job loss and economic growth in the region as a whole, right? So I think right now we’re in this moment where there is economic uncertainty and wage fear, all those sorts of things that are feeding into it, which I don’t recall that we had back then.
Listen, the market is much bigger now than it was in the nineties. Projects are much bigger. So I think it’s entirely possible that this problem feels bigger than the nineties. But relatively speaking, given the size of the market that we had back in the nineties, the number of homes we were selling back then relative to today, it probably is very similar. But back then we weren’t building the rental we’re building now, right?
Back then, and I’m probably wrong on this number, but I’m going to suggest that the amount of rental stock built from 1995 to 2000 probably represented 10 per cent of all the multifamily housing stock built. And now it’s obviously much, much different. That’s contributing. The amount of rental supply that we have on hand is contributing to the malaise in the market.
Matt Scalena: Adam, not to monopolize the conversation, but can we talk a little bit about that rental supply? Because somebody, especially this summer, I’ve had people from out of town and they’re like, “Yeah, but look at all the construction still, look at all the cranes in the sky.” And I’m consistently saying, “Yeah, that’s rental.”
Rents have fallen though for the last couple of years, and you already mentioned migration patterns and immigration being put almost entirely on pause. How do you see this playing out? And is there more rental to come? Where are we in this cycle or boom of rental construction?
Daryl Simpson: Right now there’s close to 20,000 units of multifamily rental under construction in Metro Vancouver. About 14,000 or so of those are concrete units, the balance more wood frame. There are a number of those units that aren’t delivering until 2029, but if my memory serves, you’ve got about 5,000 units coming next year and another six or seven thousand units coming the year after. So there are additional deliveries coming in future years for sure. They’re not waves, but that’s got to work its way through the system. And it will.
Adam Scalena: And what does that mean for rents, just to spell it out?
Daryl Simpson: Gosh, I don’t know that my crystal ball is that clear. But without population growth, without wage growth, and population growth is more butts in seats, more demand for housing, that’s pretty obvious, and wage growth allows people in the lower end of the rental market to move up and rent a nicer home, bigger home, closer to the urban core, whatever. In the absence of those two things, it’s easy to imagine that there’s very limited opportunity for upside growth in rents in the next few years.
That being said, I’ve said for a while, I think our federal government is going to realize that we need responsible, air quote, responsible amounts of immigration into this country to sustain and buttress our economy for the short and long term. And I think you’re going to see that. It’s not a green shoot because it hasn’t shown itself yet. But for the life of me, I can’t believe that we’re not going to begin to welcome into this country people that are going to be supportive of our economy and help us drive it forward. So I think that’s going to help.
But I don’t recall a time, in fact I’m quite sure there hasn’t been a time in this market, in Metro Vancouver, where rents have decreased, and they’ve decreased over the last year or two. That’s never happened before. And so that’s catching a lot of people off guard for sure, because you’ve always been able to depend on a floor rent.
So developers such as ourselves and our competitors are looking at the rental market today. Let’s say rent is five bucks, and you’re going to calculate an annual improvement on that rent. In the past, developers, not ourselves, but developers were forecasting a 5 per cent rent increase this year, 5 per cent next year, 5 per cent the following year, and justifying projects on that basis. So lo and behold, you’ve got rents that are $5.75 in three years and the project pencils now, because you’ve concluded that the rents are going to be there in three years when the project’s delivered and you can service the debt required to build it. Today that’s different.
So we’re flatlining our rent appreciation for the next couple of years. Well, that’s not entirely true, but this year and next year we’re not forecasting any rent growth, and really moderate rent growth in the following years. But that will change again. In 2030, 2031 it’s going to change again, because nothing is going to start. Effectively, nothing’s going to start next year. Nothing’s going to start in 2028. And we will inevitably be in a less balanced, or more challenging, housing market again in the early 2030s.
Adam Scalena: I’m just trying to help people understand what’s happening right now, where we’re seeing cranes in the sky and people building rental towers. Can you talk about why build it? What’s the exit right now for the developers that are building these projects? Is it institutional money, or are developers building to retain the rentals themselves? What’s the typical exit, and does it make sense to be building rental right now?
Daryl Simpson: I would say that it makes sense to be starting rentals next year, as I just mentioned a minute ago. It’ll make sense to start rentals next year that land in 2030, 2031, because we will come out of this valley by then.
Why would someone start a project today? Or why would someone have started it last year or the year before? The reality is it may be because they had to. You buy a development site, you put some debt on it. The debt costs you a little bit more than you thought it was going to cost you when you bought it. Your path out of that, you have to do something. You can’t just sit on it, because the land gets more expensive over time as you sit on it. So there certainly are some tailwinds pushing developers, and the institutional investors that are invested in those deals, to just get on with it.
And figuring out servicing debt in 2028 or 2029 for projects that started a couple of years ago is a more palatable prospect than trying to sell the land right now in a very constrained demand market. Does that make sense?
Adam Scalena: Totally.
Matt Scalena: Yeah, it does. So I’m just wondering about the length of the cycle. You’re thinking one of the potential green shoots is that inevitably at some point the federal government’s going to turn the taps back on for immigration. But it sounds like we’re grinding through, at least on this side of the market, for another four or five years. Is that the only factor we’re considering, or is it just the cycle we’re thinking about, like at some point this too shall change? What other factors are you considering to think that things are better by 2030, 2031?
Daryl Simpson: Sure. A change of provincial government would be number one. I’ll talk a lot about that in our time today, but a change in the NDP regime simply has to happen. We’re screwed if that doesn’t happen, in my view.
But just to bracket what I was saying earlier around 2030, 2031: those assets will perform better. Brand new rental product landing in this market that we’re in the midst of developing right now, those investments will feel better in 2030 and 2031 when those projects land than they feel today. That’s what I mean by that. That’s not to suggest that it’s going to take us five years for the market to correct, because I don’t think so.
I think we’re closer to the bottom today than we were when I spoke to you, I don’t know when that was, summer or spring last year. For sure we are. But we’re not there yet, because we’ve got a lot of product completing this year and early next that has to close, and we’ve got to get people financed and get them in their homes and turn that product over and pay down bank debt, which we’re in a good position to do.
So what are the other green shoots? We need more butts in seats to eat up this supply. We need a little bit more time to eat up that supply. We need people to believe in a more positive future in this province. And right now, I don’t think there’s ever been a time in my lifetime when there’s been more despondence and concern about how the hell we’re running this economy and how we’re taking care of people in this province. I think it’s shameful.
And without changes, I think you’re going to see a lot change. I remember in the early 2000s when the NDP got punted, it was a light switch. It was a light switch that went on. And I do think that will happen again this time. It may not be as profound a kickback, but I think it’s going to be profound. And I’m not running for office.
Matt Scalena: I was curious to hear if Townline, or if you, are thinking about the relationship between the actual pre-sale market and the rental market. Because I think in the first two quarters of this year, I don’t think there was a concrete tower launched for selling condos. But we’re talking about grinding through rental properties that are still being built. And of course, at least on the investment side, which is usually the people that are buying tower condos, you want to see at the very least some potential for appreciation, but at least rents not declining, right? That’s one of the other factors. So are you thinking of those two things in conjunction? How do you think about those two parts of the market speaking to each other?
Daryl Simpson: At times one is an indicator of the health of the other and vice versa. When there’s a strong rental market, there is a strong condominium investor market. And when the opposite happens, there’s a resultant correction in the other. So I do think that we need to see stability in the rental market before we see significant upward movement in demand for condo pre-sales.
Because as you guys well know, pre-sales generally, in my career, have been supported to a large degree by investor buyers. And we can talk about, you know, people say speculators are bad, investors are bad. Well, that’s BS, because we need investors to put down their risk capital to help these projects get on the board so that five years later someone has a home to either rent or buy from them. So we need that.
Anyway, as I said, when rents begin to stabilize, you’ll see investors start to look again. But we also need, I would argue, reform of the Residential Tenancy Act. It needs to be easier to be a landlord. And I may have said this to you before, and if I did, I apologize for repeating myself, but it’s terrible to be a tenant with a bad landlord. It’s terrible. And we need to protect those people from bad landlords.
But we also need to give landlords some certainty and control over the capital they’ve risked to buy that home and put it in the rental market. And right now, there are a lot of people that are pretty disillusioned with the Residential Tenancy Act and the constraints that it puts on a landlord in terms of rent increases and dealing with problem tenants, et cetera. I would argue that it’s too heavily slanted in favour of the tenant.
Again, we need tenant protections because there are bad landlords out there. But there are some bad tenants too. And mom and pop who save up retirement money and invest in a condo, they need to have assurance that they’re not going to get swindled by a tenant as well. So I think that’s really important.
Adam Scalena: Shifting gears a bit, Daryl. Matt and I have been talking a lot lately about lessons learned from this downturn, and about advice that we’ve given over the years and how we might change that or think about it differently. Given your vantage point, what are some lessons learned as someone leading one of the larger development companies in the city?
Daryl Simpson: Wow, lots of lessons these days. I thought I was getting too old to learn new lessons, but I’m definitely not.
I think one of the biggest things, and I say “we” in the collective sense, is that we as an industry took our eye off a few balls. One of them was that we allowed government to be an active participant and profiteer in the housing industry. So while population exploded and while interest rates dropped, we didn’t pay enough attention to what was really happening in the background. And so those government extractions just kept going up and up and up, and created a cost of delivery crisis, not a supply crisis. They created a cost of delivery crisis. We took our eye off that ball.
And so right now you’re seeing our industry advocate and push back on government saying, “No, no, no, you have a really strong hand in this problem.” There’s a lot of culpability here on government, because government was all too apt to insert themselves into the value chain, or the cost chain, and take out of it. And we have to push back on that.
So I would say more active advocacy for our industry, and for consumers and renters that are simply having to pay too much for homes. They shouldn’t. Government should not be taking over a third of the cost of a home and lining their pockets with that money. Certainly that money’s got to come from somewhere. But really, those funds in the municipal coffers should come from property tax revenue. It shouldn’t come on the backs of new homeowners.
What they’ve done, which is a little sneaky in my mind, is they’ve really masked their own lack of governance and fiscal prudence by borrowing from the pockets of new home buyers to pay for the inefficiencies of municipal government. So we need to pay more attention to where government is active and where they need to get out of the housing business. Really hard to do that. That’s number one.
Number two, I think if developers are honest with themselves, we took our eye off the ball a little bit in terms of what consumers really wanted. So you started to see towers just get taller because they could. You’re chasing density, more supply, more supply. Units got smaller in an effort to try and make that $1,000 a square foot or $1,200 a square foot end price feel smaller. So suites got smaller, to the point where some of them are really not all that livable. And so there’s a livability problem in some of the older cohort of product.
I was talking with my daughter and her friends a couple of weeks ago about their propensity or desire to own a condo today, and I was contrasting it with mine or my wife’s when we were in our mid-twenties. When I was in my mid-twenties, I very much wanted to have a bright, shiny, brand new condo. At the time it would have been maybe Kits or Yaletown. Now consumer demand is changing.
I’ll go off on a bit of a tangent here, but young people shop in thrift stores and want stuff that’s got a patina to it. They want vintage clothes and analog mechanical cars. There’s this whole movement to have things that were handmade a bit and had a little bit more soul to them. I think our desire as an industry to chase, or perhaps cater too much to, an investor buyer and not an end user caused us to move our product away from what people really, really wanted.
And I think that’s one of the things you’re seeing now in the standing inventory that we have in this market. There’s a reason why those homes weren’t bought. They’re probably the homes that were less desirable than the homes that were bought on the opening day of a condo launch. So I think shifting consumer demand is definitely a thing. We need to pay more attention to that, to what consumers and end users really want. And we need to be very careful when government starts putting their hands in the cookie jar. And it’s not our cookie jar. It’s the consumer’s cookie jar. We need to be careful with that.
Adam Scalena: I can’t help but think that over the years, at least since our initial conversation, Townline has diversified quite a bit, and I’m thinking specifically of non-market housing. Have market conditions directed where you’re active?
Daryl Simpson: Absolutely. Well, we have always been active in the non-market space. In fact, we were a forerunner there. Right now you’re seeing a number of our market developer competitors looking for opportunity in the non-market housing space. We’ve been there for, gosh, close to 20 years, since Rick Ilich and his wife Lauren started TL Housing Solutions.
So we’ve been there for a long time. But certainly the challenges of the day mean that there is an outsized opportunity in the non-market space to keep people employed and keep shovels in the ground relative to what it was three or four years ago. No question.
And to the question of diversification, the fact that we are now continuing to invest in our third-party construction business is further evidence of that too. Most people listening to this would not know that Townline builds for other developers. But we do. And we’re getting busier and busier at that.
There are developers that are interested in having a different type of general contractor or construction manager manage their asset. There are developers that appreciate the fact that we also have a developer-centric mindset when it comes to putting projects together and getting them built on time and on budget. So bringing that developer, in-house construction mindset to the third-party construction world is a big point of differentiation for us. And that’s where we’re seeing a good amount of opportunity right now.
And I should say, not just from developers, because the other thing that’s happening is you’re having lenders who have taken back projects. Lenders have been turned into developers. They own them, and they have problems that need to be solved. And the fact that we have in-house and third-party construction expertise, and development management expertise, and in-house sales and marketing, all these things as a wholly integrated developer, the fact that we can bring that to a lender is a huge point of value for them. So there’s a fair amount of growth in that area too.
Now that’s somewhat reluctant, because it means lenders have a problem and it’s a symbol of an unhealthy real estate market, right? You’ve got lenders taking back land debt and owning projects now. But in the short term we’ll be pretty active helping those groups out too.
Matt Scalena: How does the industry look different when we come out of this? I’m thinking, are a lot of the smaller players gone? It sounds like Townline’s busy, but I can’t help but think, especially last year, there was talk of massive layoffs, some very loud layoffs and then others quiet. I feel like we’re consistently hearing about new foreclosures on projects right now. How does the industry change? Will everybody be better for it? What does it look like?
Daryl Simpson: That’s a great question, and there are a lot of facets to the answer. So I’m going to start actually on the construction side of the business for a second.
There is going to be a shortage of work in the next year or two for subtrades. And so there will be subtrades who are at the same time aging out. You’ve got principals of those companies that are my age or older saying, “You know what, I don’t know if I want to hang around for the next turn.” So you’re starting to see some consolidation and some retirements on the subtrade side.
I think the pool of subtrades that we have to draw from and to work with is going to be smaller in the next two or three years than it is today. And what does that mean? It’s actually going to create more competition for their work, and construction prices in the medium term, two to three, four years out, are not going to be lower, they’re going to be higher, because there are fewer subtrades to choose from when we’re tendering a job. So I think you’re going to see attrition on the subtrade side in the construction world. Maybe we’ll talk later, if we have time, about overall construction costs, which I’m happy to talk about.
I do think there are large institutionally backed development companies that aren’t going anywhere, that have relatively strong balance sheets and a good pipeline of good land, who will be around. But there certainly will be some that are caught in the middle. The guys that are doing a small apartment building, a couple of duplexes, some single family homes, those guys will probably be okay, hopefully. It’s the guys in the lower end of the middle, I think, that are at the most risk, because they typically don’t have a ton of equity in their deals. They typically have a little more debt and they’re more exposed.
So if you look at some of your colleagues who specialize in the foreclosure business on the land side, most of the dirt that they’re looking to sell now was previously sponsored or owned by a smaller-tier, sort of C-tier or B-tier developer, in most cases, with some exceptions. So I think you’re going to see some attrition there too, for sure.
I also think that the market, when it returns, won’t return in exactly the same form. And that’s the spirit of your question. I think in the condo world it’s going to be a long time until developers open up a sales centre and sell a project in a week, or pre-sell it out of their boardroom. All those things that were happening back in the hottest market we’ve ever seen in 2022, it’s going to be a long time till that happens again.
I think that we are moving back towards a more balanced market condition, where we may sell 25 or 30 per cent of our projects and we need to put more equity in so the bank will lend on the balance. So instead of having a project 90 per cent pre-sold or 80 per cent pre-sold or even 50 per cent, I think in the next phase of this market you’re going to see pre-sales with lower percentages, a smaller pre-sale stack, where developers have to put in a little bit more equity. And banks are going to have to be a little bit more patient. Patient’s the wrong word. Banks are going to have to be a little bit more accommodating, acknowledging that. Because I think it’s going to be a while until we get back to that feverish, lineup-around-the-block, buying suites sight unseen kind of condition.
So that’s what we’re planning for. It’s real homes for real people over a reasonable amount of time, quite frankly, back to the way it was in the early 2000s or in the nineties. And by the way, there was nothing wrong with that. The market went up two or three, four or five per cent at the most, and it was predictable, and it created a reasonable level of affordability for people. It’s not a terrible thing to get back to that. As much as it’s nice for developers like ourselves and our competitors to sell a project out on day one, I think that’s going to be a while till we get back to that.
Matt Scalena: Thinking about our side of the business, the resale real estate business, one positive is that the number of people in the business is shrinking, but I feel like the quality is actually improving. The order takers are leaving, the opportunists that showed up for two or three years. I wonder if it becomes an area of higher talent and a more craftsman-type approach. I’m trying to look at the positives here.
Daryl Simpson: Listen, I’m not an expert in your business at all, but the value of a realtor, it seems to me, has always been your ability to provide information and counsel that your clients simply couldn’t access themselves over a reasonable amount of time. If somebody didn’t want to use a realtor and wanted to investigate the market for six months and do nothing but that, maybe they could create some reasonable facsimile of the expertise and wisdom you guys have. But tough to do.
Now it’s way easier to do that. Or certainly I would imagine consumers feel as though it’s easier to do with AI and everything else. Presumably people are saying, “When Matt and Adam tell me this house is worth 1.8, are they right?” And the prompts that you can offer and the information you can get back, I suspect, is a real challenge for you guys right now, as it is for us on the consumer side.
Adam Scalena: AI kind of sucks at market analysis, but your point is taken. I think what Matt was getting at more so is, are we left with tier one development companies at the end of this?
Matt Scalena: Yeah, it’s a trimming-the-fat kind of thing. You come out of this stronger, but also with people who, at least on our side of the business, there were people that showed up and now they’re in Costa Rica selling coaching platforms. They weren’t actually interested in real estate in the same way that presumably the three of us are. So I guess I’m trying to find the silver lining, essentially.
Daryl Simpson: I think so. When the market was white hot, and it doesn’t seem like long ago, four years ago in 2022, we think of ourselves as a developer that does what we say we’re going to do and does the right thing as often as we can. That’s sort of our North Star. We’re competing across the street from a developer who may not share those values, and yet the consumer is paying the same price for our product versus theirs. And it shouldn’t be that way.
So that hot market equalized talent, skill, responsibility, accountability, quality. And that’s not going to be that way for the next few years. The better developers are going to find absorption, or make a little bit more, as they should.
Matt Scalena: Actually, it’s funny, this brings me back to Colin Bosa being on the show, which was maybe 2018. That was a long time ago. And his point was that in such a red hot market, the differentiation between builders was not there, and it should be. It was actually a frustrating aspect of a really hot market.
Daryl Simpson: Yeah, for sure. So it won’t be that way in the coming years.
Adam Scalena: Daryl, I do want to circle back to construction costs. Right now, obviously with incentives going on in the Lower Mainland, we used to talk about a thousand a foot, and below a thousand a foot it was very challenging for anything to be delivered. Now we’ve got some projects that are selling significantly below a thousand a foot after you take into consideration the incentives and the prices. So where are we at with construction costs? Have construction costs come down?
Daryl Simpson: No question, they have. It’s our belief that there’s value for us in starting projects pretty soon. So if we’re taking the savings, towers used to cost, say, high $400 a square foot to build, and certainly some of them are well in excess of that, but a middle market tower, if you were building at the height of the market, let’s say you were pro forma-ing $475. Today you’re pro forma-ing $400, $425. So there’s a savings there for sure.
But to my earlier comment, I don’t think that savings is going to be there forever. I don’t think those numbers got reset. They’re going to go right back up fairly quickly when the market provides opportunity for developers and lenders to get going with projects. And when that engine starts up again, I think you’re going to see it go bang, right back up to the high fours again, to use middle market concrete as an example. So I think those savings are somewhat fleeting.
The savings are coming from excavation and shoring, site works, form work to a degree, glazing systems. But as soon as you start getting into mechanical and electrical equipment, that requires a lot of factory production that’s generally made outside of Canada, that’s subject to tariffs and shipping and all sorts of other issues. I know those divisions in our budgets haven’t changed much at all. In fact, those suppliers are holding on to their numbers. They’re not capitulating in terms of cost much at all.
The savings are coming from generally the early trades. So if someone’s got to deliver an HVAC unit in three years to a building, they have no idea what that’s ultimately going to cost them in three years. And so they’re reluctant to pass any savings on right now.
Matt Scalena: Maybe switching gears, Daryl. I’m assuming you have some thoughts on the developer condo bailout, as some people are calling it.
Daryl Simpson: You used the B word. I didn’t. You just called it that.
Matt Scalena: I’m parroting what I’ve read. Is that what it is? You’re what we’d call an insider. Did this take you by surprise? Where are we at with this? What do you think of it?
Daryl Simpson: There’s a ton of questions in there. The most important one is, what is it? I don’t know. Does anybody know what it is? I know what the provincial and federal governments suggested it could be, as a result of multiple press conferences to try and figure out what the public wanted. But we as an industry did not advocate for this. UDI did not advocate for it. There was no consultation around that program within the development community.
And when the question got asked about what the development community would recommend to stimulate activity to eat up some of this supply, our response was, well, I shouldn’t speak for others, but I know what I’ve said to that question over the last year: provide a tool that all consumers or renters can use. Don’t pick winners and losers.
This government’s really good at picking winners and losers. “We’re going to give this amount of money to this group and we’re going to give this amount of money to that group for this program,” instead of creating a playing field that’s level and beneficial for everybody. So we would have wanted something akin to what they did in Ontario. HST relief across the board. Buy a home up to 1.8 million bucks, you don’t pay any HST. That’s big. We need that, and on rental too, by the way. They did that on rental. Stimulate rental construction.
So we did not ask for the B word. And quite frankly, when it came out, we were all shaking our heads going, “What the hell are they thinking? How are they going to make this work?” First of all, how are you going to buy the units? How are you going to determine whether you’re buying them at wholesale prices or not? And who’s going to be the arbiter of that value? Are you going to hire a broker? Are you going to hire a realtor to do it? Are you going to hire an appraisal firm? How are you going to determine whether you’re getting great value or not? Government’s not good at doing that. So they need to hire someone to tell them that. So how’s that going to work?
And then what are they going to do with those units of housing once they own them? They didn’t know whether they were going to sell them to middle-market consumers, nurses and first responders and teachers, although they tossed out those words. How the hell are they going to actually get them in the hands of those people equitably?
And then if it’s a rent to own, well, that rent to own is a whole other thing. Rent to own doesn’t really work. And then if they were going to actually lease out those homes, I just think it’s a travesty. How would you feel if you bought suite 2401 in a condo building and you’re living there with your family, and you found out tomorrow that the provincial government now owns the unit next door and is now leasing it to a non-market subsidized tenant? What does that do to the value of your suite? And what does it do to the value of your building? It’s not good.
So I think that was a very ham-fisted, non-elegant way of trying to figure out what voters in British Columbia wanted. And I don’t think Carney knew. I think he literally said to Eby, “Listen, we’re going to do something for you like we did in Ontario. What do you want?” And Eby said, “Well, what if we buy a bunch of distressed inventory?” Somebody gave him that advice. I don’t know who it was. It wasn’t me. And it wasn’t reflective of what the industry wanted. The market should figure itself out.
Matt Scalena: So in your mind, does this actually happen? It feels like there was this big bombshell. We’ve talked about it now for six weeks at least, I would say, and there seems to be no further clarity. When does this happen? Do you think it actually happens? Or is this just another one of those, “Man, that was stupid, let’s slowly and quietly walk this back and change it”?
Daryl Simpson: I don’t know this, but I firmly believe that that program, that $1.3 billion, was it $1.3 billion? Whatever it is. The provincial government is going to stand in front of a microphone and say they’re doing something to help the housing market, or renters, or tenants, or First Nations developers perhaps, or non-market developers, who knows? That money is going to find its way into the system and they will have press conferences about it. But I don’t think it’s going to be a broadly distributed instrument across a number of markets. I think it’s going to be really siloed, but I don’t know where.
So I sort of share your thoughts. It also could just kind of go away. It might just fade into the background.
Adam Scalena: That’s happened a few times.
Matt Scalena: I feel like I’ve fielded this question a number of times from people selling or buying, just, “What do you think that does to the market?” Presumably we’re all of a like mind: probably not much, right? The impact is not going to be felt, at least not in the short term, if at all.
Daryl Simpson: Well, the impact of what? The originally conceived bailout program?
Matt Scalena: Yeah, I think most sellers or buyers, just regular people in the market, are asking what this does to the market. And I feel like the answer is probably not much of anything. But what do you think?
Daryl Simpson: I think it actually confuses the hell out of the market. At a time when a lot of your clients, to your point, are looking to you to say, “Do I go left, do I hold, do I go right? What should I do?” I think the prospect of a condo bailout and the provincial government buying market housing and turning it into non-market housing somehow is confusing as hell. And I think it’s one more reason for a consumer or a renter to not make a decision. So it’s not helpful at all.
And if they did do it, I think it would be hurtful, quite frankly, for the reasons I mentioned earlier. How do you pick winners and losers? Buying swaths of inventory in a building that didn’t previously have non-market housing in it could reasonably affect the value for the market buyers in that building. You wouldn’t be too happy if that happened, right? So I think it’s grossly unfair.
I also think, and I’m harping on this government now, but I believe this government wants to depress asset values. And I’ve said this for a long time. In fact, the housing minister issued some content out on Instagram yesterday, taking a bit of a victory lap on the fact that rents are continuing to come down as a result of provincial government policies. I mean, the amount of rental supply that’s in the market is a result of federal programs, primarily CMHC, and the private market making decisions years ago to create housing stock. Now there’s a little bit too much of it right now, and that’s causing rents to come down because we don’t have enough bodies to fill those apartments. That has nothing to do with the province. So they’re taking a victory lap on that.
I see our provincial government as arsonists that masquerade as firemen. They create this really untenable, unhealthy economic condition, and then want to come in and tell everybody how they’re fixing it. And it bothers me.
Adam Scalena: That might be the quote of the decade for this podcast. Maybe we leave it there, because I don’t think we can do better. Arsonists masquerading as firemen.
Daryl, we have this segment called the Five Wire, five light-hearted questions that we end every show with. Can you stick around for that?
Daryl Simpson: Yeah, of course.
The Five Wire
Adam Scalena: Question number one. One book that you would recommend for our listeners that you’ve read recently?
Daryl Simpson: The book I’m reading right now, I’ll get the title wrong, is How Leaders Can Inspire Accountability, written by a business coach here in BC, a guy named Michael Timms. It’s less about business, more about how to manage your teams and be accountable as a leader and create accountability from all your teams. I’m almost at the end of it and it’s been great. I hope he’s not listening. It’s not the best book I’ve ever read, but it’s a really good refresher and reminder, and there are some good tools in there for people who are leading teams. How Leaders Can Inspire Accountability. Local guy, BC guy.
Matt Scalena: In the last few years, Daryl, or at least since you’ve been on the show, what new belief, behaviour or habit has most improved your life?
Daryl Simpson: We were fortunate enough to spend some time in Italy in May with family. When I got back, I was quite relaxed. It was a phenomenal, fairly short vacation. And I was reflecting on why I felt so relaxed there. Well, because I’m on vacation and I’m in Italy and I’m with my family, and that’s phenomenal. But you live differently when you’re on vacation. You do things differently.
One of the things that I don’t do when I’m on vacation is grab a coffee cup and throw it in my car and run around and drink half of it and throw the other half out. What you do when you’re there is you sit down and you have a coffee in a cup and you sit at a nice table outside and you take 10 or 15 minutes, you watch the world go by, you’re a little more present.
So I did that. When I came back, I said, “Screw it. I’m not going to get coffee in my car anymore. I’m going to get up 10 minutes earlier and I’m going to find a coffee shop that’s open early, and I’m going to get it in a porcelain cup and I’m going to sit in a chair outside.” The weather’s been nice, it’s not January. So I sit outside, I take 10 or 12 minutes with my cup of coffee and I don’t rush as much. That is a really, really small thing, but it actually feels way better.
Adam Scalena: That’s a fantastic one. It’s funny, I’ve just been walking my kids to school all summer, one of them’s in a camp close to our house, and I’ve been walking there to drop them off and walking to pick them up. And I was thinking about the same thing the other day. I’m like, why do I feel so great? And I think it’s the walks in the morning and the late afternoon. My day’s a little bit more compressed, but subtle changes.
Daryl Simpson: There’s something about walking beside somebody when you’re talking to your kids. My kids are 19 and 23, but when you’re sitting across the dinner table talking to your kids, or even in business, it’s different than walking beside somebody shoulder to shoulder and talking that way. The dynamic’s just different.
And I remember my wife always saying that the magic moments for her, because I very rarely did it unfortunately, were walking home with our kids and the way they would unload and share about what they did in their day. It’s totally different than when you get home. I should have done more of that.
Matt Scalena: I’ve got to find the coffee spot.
Daryl Simpson: Where are you? You’re like a Fraser Street, Main Street guy, no?
Matt Scalena: Near Commercial Drive.
Daryl Simpson: Continental Coffee on Commercial Drive. Best coffee.
Adam Scalena: Continental. That’s a nice one. This seems jarring after that, but what are you binge watching?
Daryl Simpson: You know what, I’m not binge watching anything right now. We started watching Dutton Ranch. We haven’t finished it. We started that the other day, but I’m not really binge watching it. I think we’re like four or five episodes through. I didn’t power through it, so I can’t say I’m binge watching it. I’m just watching it. But it’s all right.
Adam Scalena: Have you seen The Odyssey yet?
Daryl Simpson: I have. And I thought it was fantastic. Have you seen it?
Adam Scalena: I haven’t seen it.
Matt Scalena: I saw it on the weekend. It was great. It’s funny, I left thinking, I wonder if I should pick up the actual text and read it and see how close it is.
Daryl Simpson: You’re not going to do that. I thought the same thing. I’m like, screw that, I’m just going to watch the movie again.
Matt Scalena: It was great though. Super excited about that.
Daryl Simpson: It was good. The best scene for me was when Calypso says it’s time to go, and he puts his raft together and he just kind of succumbs to the waves and gets pummeled by the waves, and he’s just succumbing to everything and letting what will be, be. To me that was like, okay, there’s a lesson in that. Sometimes you can’t fight against everything. Sometimes you just have to relax a bit. Chill out. I thought it was good. And I didn’t fall asleep, so for a movie that starts at 9:30 on a weeknight, to last a couple of hours through that and not fall asleep means it’s a good movie.
Matt Scalena: That’s actually me too, and it’s not a short movie. But no, it was great. And the last half hour, 45 minutes was just edge of the seat. So great.
Matt Scalena: Daryl, we know that you’re the lead singer of a band, and that country has been on your radar. What are you listening to lately?
Daryl Simpson: Zach Top lately. I like Zach Top, Ella Langley. Country again, country. But my playlists are like eighties rock, eighties, nineties rock. You don’t buy albums anymore, right? In my generation, you’d buy an album, you’d play it, and you’d listen to it. I don’t really do that anymore. I listen to whatever my kids put in our playlists, and thankfully they like old stuff too. They like good old music, like eighties, good strong melodies. They like Journey and Fleetwood Mac and all that stuff. But they also like modern stuff, Drake or whatever. So I listen to a little bit of everything. No concentration. I’m all over the map.
Adam Scalena: Good mix. Daryl, last time we asked you for something that you purchased under fifteen hundred dollars. We’re going to increase that. Something you’ve purchased for under five thousand dollars in the last few years that’s had a positive impact on your life. It can be an experience too.
Daryl Simpson: My son is going next week to test in a race car up in the Okanagan, and that’s his 19th birthday present. I haven’t done it yet, but that will be my answer. If we were to do this two weeks from now, that would be the answer. I can’t wait to see him in that.
Adam Scalena: Amazing. Do you get to drive as well, or are you just there?
Daryl Simpson: I am there. I don’t know if I’ve told my wife that I might be driving, so I don’t know.
Matt Scalena: Just one other question, because we always ask this and I feel like it’s worth asking you, Daryl, before we let you go. Forecast. Let’s talk the rest of this year, 2027, one, three, five years. What does general pricing do in Metro Vancouver?
Daryl Simpson: I think pricing continues to come off a bit over the next six to twelve months. Listen, you’re asking for a really precise answer for a very complex thing. But if I were betting, I would say prices continue to come off a bit. And maybe this time next year they flatten out and start to show some signs of recovery.
I think back to the late nineties, early 2000s. By the mid 2000s, 2004, 2005, the market was pretty hot back then too. We had a lot of Korean immigration, mainland Chinese immigration was really starting then, Persian immigration. Whenever things got rough elsewhere in the world, a North Korean missile test, sabre rattling between the West and Iran, or Israel and Iran, whenever that happened there were always good things that accrued to this market. There were people who lived here who wanted to invite family here who bought more real estate, or people who didn’t live here who bought real estate here and invested and said, “I want to get my family’s nest egg out of that part of the world and move it to a friendlier place.” And Vancouver was a friendlier place, obviously, and still is.
The world today is a far darker place, arguably, than it was 15, 20 years ago. There are so many people having incredibly difficult lives right now. I think that once again, once we welcome into this country some investment and a reasonable, responsible amount of immigration, we could be very, very healthy very, very quickly again. I absolutely believe that will happen, because I don’t think things in the Middle East are going to get any better anytime soon, sadly. I don’t think that things south of the border are going to solve themselves anytime soon, sadly.
And I think relatively speaking, the brand of British Columbia, despite our warts and our provincial government and us telling people we don’t want foreigners here and all those sorts of things, once we get through that, I think we’re as well positioned as we’ve ever been on the global stage to have a strong economy with a mosaic of people from all around the world. It’s going to take us some time to get there.
Matt Scalena: I’m glad I asked. That’s a great way to end it. Daryl, how can people find out more about what you’re up to?
Daryl Simpson: I’m not that active on LinkedIn, but I probably should be more. If anybody’s got any questions, I’m at daryl.simpson@townline.com. That’s the best way to find me.
Adam Scalena: Amazing. Well, thanks again for the time.
Daryl Simpson: Thank you guys. Nice to see you again. All the best.


