Table of Contents
Listen On: Apple Podcasts | Spotify | Google Podcasts
Guest Information
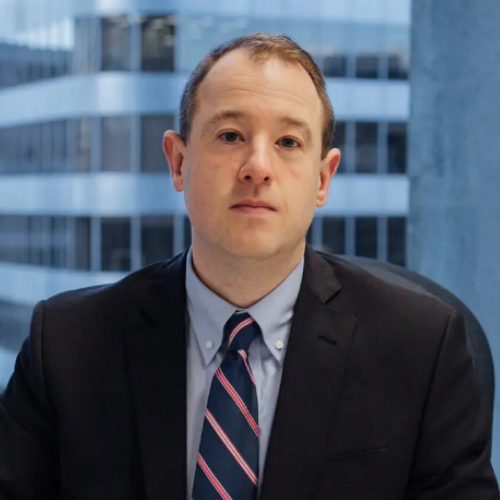
Brendon Ogmundson
Brendon is the Chief Economist for the BC Real Estate Association and specializes in macroeconomic forecasting and housing market analysis. He is responsible for communicating trends and producing forecasts for the BC housing market, and for forecasting the BC, Canadian, and US economy. He is a member of the BC Ministry of Finance Economic Forecast Council and is also a contributor to the Philadelphia Federal Reserve’s Survey of Professional Forecasters.
Episode Summary
BCREA Chief Economist Brendon Ogmundson joins us to talk about the latest interest rate hikes by the Bank of Canada and how they will change the Vancouver real estate market this fall and in the years to come. Did the bank go too far? Is there any hope for a housing supply spike? And how much worse can housing affordability really get?
Who is Brendon Ogmundson?
I’m the Chief Economist of the BC Real Estate Association. We do all things advocacy for realtors. Our analytics team does a lot of research around supply and other topical, qualitative research topics.
How’s the market?
The 2023 real estate market has been pretty weird. In January, we were thinking the economy would slow down and we might see a recession. Then we thought rates would start to come down in the second half of the year.
That was partially true. The first few months of the year were very slow. But things started to pick up in the spring, despite nothing changing to drive sales. Then the Bank of Canada raised rates in June and July, bringing us back down below normal.
As of July, we’re about 10-15% below normal sales volumes in Vancouver. But compared to the start of the year, when we were 30% below, we’re doing okay.
There’s still a lot of demand out there. The problem is how do you translate that demand to sales with an 8% stress test?
How are we doing with housing supply in Vancouver?
It’s the same story. We’re at about 10,000 active listings in Vancouver but need to be at 15,000 to be healthy. We haven’t been there since 2015. For new supply, we’re building a lot but we’re not getting to market fast enough.
Will the Bank of Canada raise interest rates again?
The two quarter point hikes by the Bank of Canada in June and July really changed expectations for investors. We saw a huge run in five year bond yields, which had been falling prior to those hikes. Not only did the Bank of Canada raise rates but they pushed their inflation target from 2024 to 2025. I don’t think they’ll start cutting until they hit that target.
Right now we’re seeing a 51% chance of another hike in September, which is unhelpful. Inflation is at 2.8%, or 2% if you strip out mortgage costs. Core inflation is between 3-4%, which may indicate another rate hike.
Overall, it does seem likeinflation is back to the range we want it to be and the economy is slowing. If we see weak job numbers, that might push a rate hike off the table.
I think the Bank of Canada should not raise rates again in September. They’ve done enough – the last two rate hikes may actually have gone too far. I don’t see a need, but that doesn’t mean they’re not going to do it.
Why do you think the Bank of Canada went too far?
It takes a while for interest rates to work through the economy. So the changes we’re seeing right now either mean monetary policy doesn’t work or the pandemic broke a lot of things. The pandemic brought us forced savings, which keeps consumption growth afloat, supply change delays, etc.
Consumer spending should be falling at this point but it’s not, I think because those savings are acting as a buffer. The Bank of Canada knows this, but they need to give it time to work itself out of the economy.
These high rates are going to drag down investment on housing, which we badly need. We’re going to see building starts slowing. All the starts we’re seeing now were planned years ago. But we may be in a situation where projects that were supposed to start in 2025 get shelved or don’t happen, which just causes more inflationary pressure on housing.
If we have a massive housing supply deficit, and interest rates are only going to make that worse, it’s going to cause a rise in rent and prices.
Is there another moment that has been as tough as this moment for the Bank of Canada?
I think the 2008 financial crisis was more difficult than this moment and more immediate. But this is certainly a tough time. You have to remember that the Bank of Canada is legally mandated to keep inflation at 2%; that’s their job.
We haven’t been through this in a long time so people forget. But this is how monetary policy works. We have to do painful things to bring inflation down but no one has experienced that in 20 years.
You can influence inflation by slowing the economy and impacting expectations. But the average Canadian is only looking at gas prices and grocery prices, basing their inflation expectations off of that. So it’s tough for the Bank of Canada to influence those expectations.
What role does the housing market play in the BoC’s decisions?
30% of CPI is shelter. So a lot of housing pressure on inflation will drive the bank to raise rates. They don’t raise rates based on sales information or something like that. That said, I don’t think they were happy with the recovery we saw in the housing market. I think they’d like to see prices stay flat.
Usually when mortgage prices go up, house prices come down. But right now, both are rising, which is unusual.
It seems the immigration policy by the federal government and the monetary policy by the federal bank are at odds.
The Bank of Canada is trying to slow the economy and slow demand on housing while the government is trying to speed up demand and are putting a lot of pressure on rental housing with their immigration targets. That is going to drive up rental costs and feed inflation. But to the wider economy, it may be more neutral because immigration will impact the job market.
Why is housing inventory so low? Is there any hope for a spike?
We did some research on new listings, which have been low for the past year. One of the reasons why inventory is low is the high employment rate. The labour market is really strong; people usually list their home when they lose their job.
Another factor is the lock in effect. If you got a mortgage in 2020 under 2% and now want to sell your home, porting your mortgage might be difficult and you’ll now have part of your mortgage at 5.5%. So people don’t want to sell and have to buy again at higher interest rates. Our model found that explained 20-30% of why listings were so low.
Lastly, low activity begets low activity. You can’t sell your home if there’s nothing out there to buy, so you don’t list. This is the factor that can recover, like we saw in May and June. But because rates are high and unemployment is low, we’re not expecting a huge inventory spike. We’d only see that through adverse economic effects, like a recession, but I don’t see that in the cards.
New listings are only now getting back to normal after a very low year. Some markets are still well below normal.
So in sum, housing inventory is low because of:
- The strong labour market
- The lock in effect
- Low activity causing more low activity
Where are we 6-12 months from now?
We saw declines once the Bank of Canada started raising rates but they didn’t last very long because we don’t have enough supply. I don’t see us getting to a point of oversupply in Vancouver.
By the end of 2024, we could potentially see inflation back down under 2% and the unemployment rate could be slightly higher, around 5%. The Bank of Canada could then start cutting rates and we’d be looking at a more positive 2025. But even if the Bank of Canada cuts 200 basis points, that’s only an 80 basis point reduction in the five year fixed rate because the yield curve is inverted.
Even if the Bank of Canada starts cutting rates, we are still going to be in a situation with much higher rates than anyone in this market has seen in 15 years.
Rates are going to come down eventually; the Bank of Canada wants their overnight rate to be 2-3%. But it is going to take time and it won’t mean as much relief as people might think.
What is the effect of immigration on housing supply?
1.5 million sounds like a lot of people but some of those people are already here, as many as 40%, and some of those people live in the same household. So the increase in housing demand is probably 20,000 households or so.
We’d need to see a record amount of housing supply created from now until 2030 to offset the impacts of immigration. If not, that is just going to drive prices up.
How much worse can affordability get?
Our model shows that by 2030, if we don’t offset the increased demand with more supply, we’ll have a mortgage to income ratio of 60% on average.
In Vancouver, 40% of people don’t have a mortgage and so aren’t impacted by interest rates. They’ve been in the market a long time and have built up equity. They can easily afford whatever they want, which complicates things.
For first time buyers or younger buyers, it’s pretty frightening. Your mortgage is really high and you have to qualify at 8%, which is really hard. We’d expect to see sales activity coming down because of that.
What is Vancouver doing to increase supply?
We’re trying to do a lot of the right things, like upzoning. Though I’m not sure why we’re not just upzoning everything and letting markets figure it out. But we need both size and speed. We need to build a record amount of homes and get them to market a lot faster.
Should we expect interest rate volatility?
There was a time this spring when we saw a lot of volatility in the bond market as investors grappled with the direction of the market. Bonds are historically very boring but we were seeing wild swings. We also saw some pretty big bank failures.
But now it seems like interest rates are going to be higher for longer than expected and no one is fighting it anymore.
What is the headline for the rest of 2023?
Can we manufacture an economy that doesn’t fall into a recession? It’s hard to find balance in the housing market when supply is so low. In retirement markets, we have some areas where people are never going to sell those homes. Especially when you have big portions of your market stock in these larger homes, they just don’t turnover that often.
With low activity and even lower supply in Vancouver, I think prices will stay the same moving into the fall. We’re not going to see any relief.
We’ve been looking at Auckland, New Zealand. It’s one of the only places in the world where upzoning has been successful and they’ve kept rents stable since 2015. What would it mean if we can match that in Vancouver? Unfortunately, just average growth still sees an average price of $1.6 million by 2030, compared to $1.27 million today. We can only fix that with more supply.
Is there anywhere in BC that has more affordable housing?
The pandemic ruined the idea of affordability in most of BC as demand spread out and retirement plans accelerated. The Island and the Okanagan got very expensive. The markets with some affordability are in the north, like Prince George. There’s not a lot of diversity in product there.
Another area where you may find some housing affordability in BC is the Kootenays. Because the Okanagan has gotten so expensive, I think a lot of retirees who were thinking of the Okanagan will shift to the Kootenays. It’s beautiful and you can still get lakefront property for a lower price.
What is the most resilient real estate market in BC?
Again, it would probably be the Kootenays! If you look at sales versus averages, it looks like rates haven’t even gone up. But all of BC is extraordinarily resilient.
No one thought Vancouver would be 5-10% below its all time high. We thought rates would have a much bigger impact in an expensive market like Vancouver but that hasn’t been the case.
What data from BCREA should people keep an eye on?
We have research coming out about the new BC Homes for People plan and whether or not that could mimic results we’ve seen in Auckland here in Vancouver. Will the plan actually increase supply? That report will be out in September and I think it’s going to be a good one.
We won’t be able to fix affordability but if we can build a lot, and build it fast, we could start to bend the affordability curve. Making these changes will have a positive effect but we have to get on it!
The 5 Wire: Getting to Know the Chief Economist for the BC Real Estate Association, Brendon Ogmundson
What is one book you recommend?
Every summer I read a ton of books. The one I’ve enjoyed the most was Martin Short’s memoir, I Must Say. It’s a really good read! It’s really funny but also sad.
What new belief, behaviour or habit has most improved your life?
Maybe I’m losing my belief in monetary policy! I might have to get a cabin in the Kootenays and just mutter to myself.
What have you been watching lately?
I liked Oppenheimer, maybe because I’m a middle aged dad. It’s wild that a movie this big is about physics and the commerce cabinet. We also have been watching The Bear, which is phenomenal!
What are you listening to?
One of the best parts of The Bear is the soundtrack. So I found a Spotify playlist where someone put together all of the songs from season one and two. It’s so good!
What is something you’ve purchased for under $1500 that has had a positive impact on your life?
We got this float pool that was only $250! It’s above ground and perfect for just two floaties and reading all summer. It’s wonderful.
Episode Host
Adam Scalena
Adam is a full-service realtor, specializing in Vancouver’s best areas. His systematic approach to real estate and dedication to his clients has consistently placed him within the top 10% of realtors operating within Greater Vancouver.
Matt Scalena
Matt is real estate obsessed and considers himself a lifelong student of the Vancouver real estate market. As a co-manager of the Scalena Real Estate team, Matt prides himself on expertly advising buyers and sellers on all aspects of the fast-paced, dynamic Vancouver real estate market. He is present at every stage of the process, from that first phone call or email right through to when keys are exchanged between sellers and buyers.
Sponsors